Indian investors can buy freehold property in Dubai Hills Estate, and the realistic budget is the purchase price plus the 4% Dubai Land Department (DLD) transfer fee and several smaller charges. A cash buyer should plan for roughly 5% to 7% above the price, while a mortgage buyer needs that amount plus a deposit set by the lender, often 20% to 50% of the value for non-residents. Exact terms change, so confirm current figures with a licensed advisor before committing.
Why Dubai Hills Estate Appeals to Indian Investors
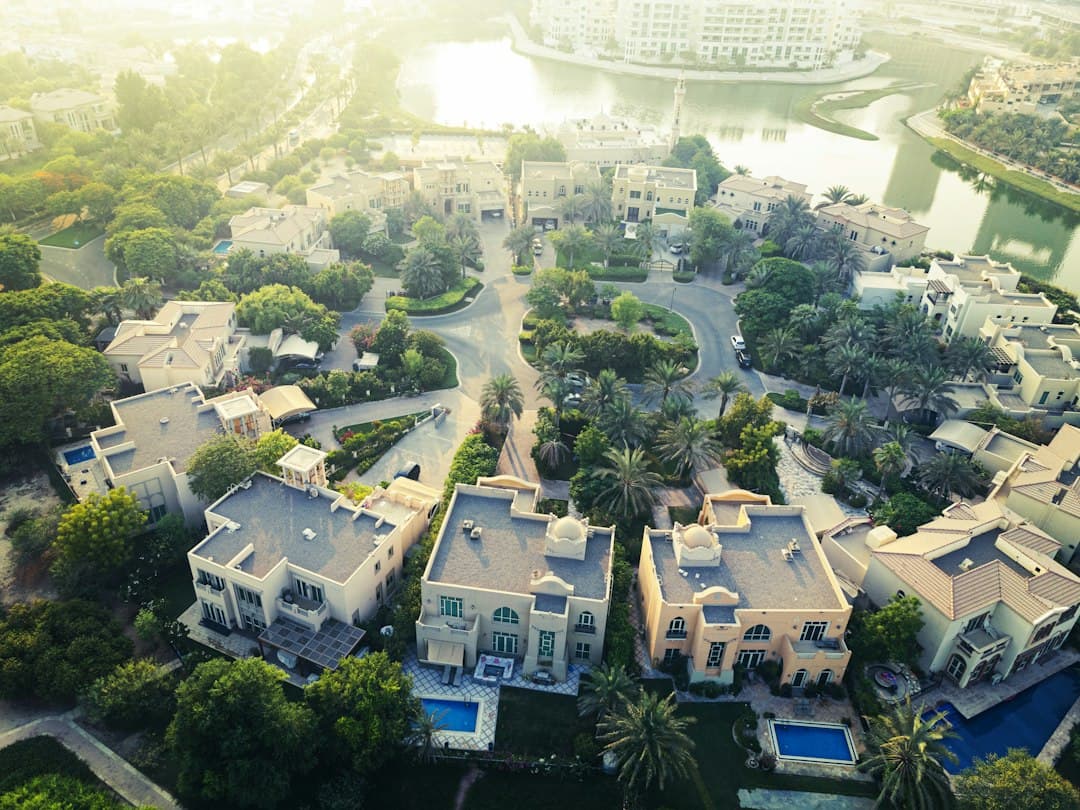
Dubai Hills Estate is one of the most established master communities in the emirate, with a golf course, parks, a large mall and a mix of apartments, duplexes and villas. Many Indian buyers are drawn to it because the area has a deep resale market and a broad tenant pool, which makes it easier to rent out and eventually sell. You can read more about the neighbourhood itself in our overview of Dubai Hills Estate.
Indian nationals are generally able to buy freehold property in designated freehold areas, and Dubai Hills Estate is one of them. Ownership is registered with the DLD, which gives you a formal title deed. Even so, the rules around mortgages, residency and company ownership are more detailed than the headline statement suggests, so it pays to check each point.
How Much Money Do You Need to Invest in Dubai Real Estate?
The honest answer depends on whether you buy outright or borrow. The purchase price is only the starting point, because transfer costs and set-up expenses sit on top. Once you add them up, the true cash requirement is almost always higher than the figure a seller quotes.
Cash Purchase: The Full Budget
If you pay in full, your main outlay is the price plus the closing costs. These are the main items to budget for:
- The purchase price, paid to the seller through the agreed payment process.
- The 4% DLD transfer fee, which is the largest single cost and is usually paid by the buyer, although the split can be negotiated.
- Administrative and registration charges, which are smaller fixed amounts payable to the DLD and related bodies.
- Agency commission, where applicable, which is often around 2% of the price and sometimes shared or paid by the seller.
- Service charges, which are annual running costs rather than a closing cost but still belong in your plan.
A full breakdown of each line item is available in our guide to every fee in a Dubai Hills Estate purchase. Reading it before you make an offer helps you compare sellers on a like-for-like basis.
Mortgage Route: Deposit and Loan Limits
Non-residents can usually get a Dubai mortgage, but on tighter terms than residents receive. Lenders typically cap the loan-to-value ratio well below the level offered to UAE residents, so the deposit you must find is larger. Lenders also look closely at income, debts and the source of funds.
Because lending rules and indicative rates change, treat any percentage as a guide only. Our overview of whether a non-resident can get a mortgage in Dubai explains the general framework, and you should confirm the current limits directly with lenders.
Rules on loan-to-value, transfer fees and visas can change. Before you sign anything, confirm the current position with a licensed real estate advisor or through official DLD and lender channels.
A Worked Example: Budgeting for a One-Bedroom Apartment
Consider a one-bedroom apartment in Dubai Hills Estate priced at AED 1,500,000. Typical one-bedroom prices in the estate run from roughly AED 1.0 million to AED 1.7 million, depending on size, building, view and condition. This example is illustrative only and not a quote for any specific unit.
If you buy in cash, the DLD fee alone would be AED 60,000. Adding smaller administrative charges and any agency commission you agree to pay could bring the total outlay to around AED 1.6 million or more. If you take a mortgage at a